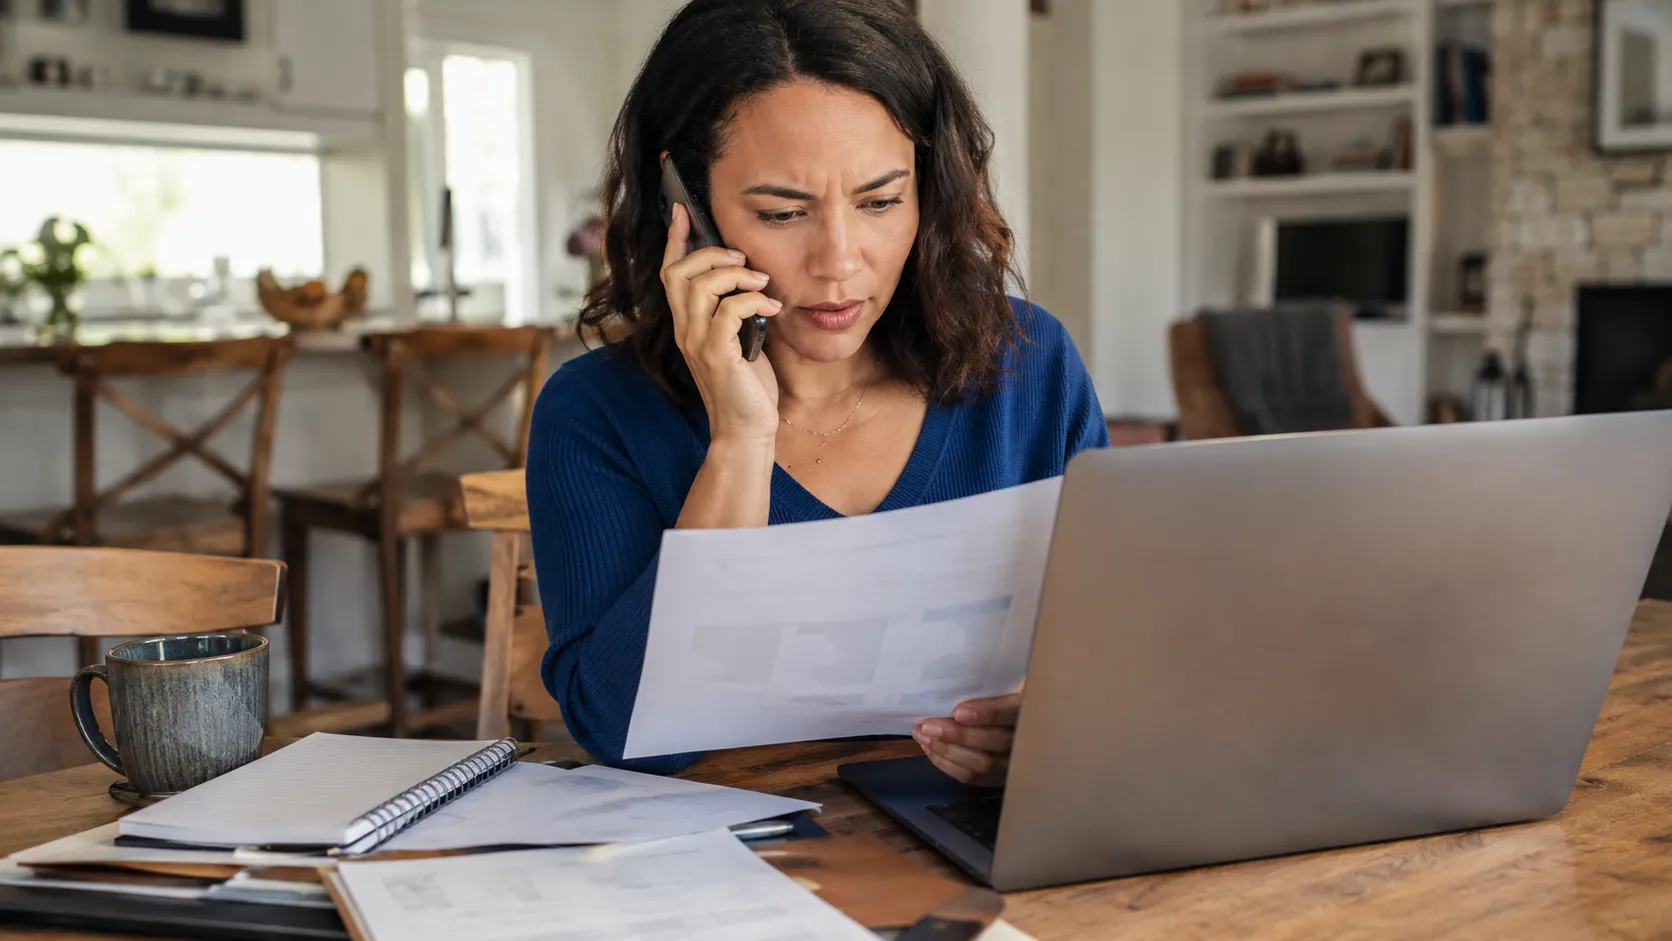
Placing a fraud alert can be an effective way of dealing with inaccuracies in a credit report when those inaccuracies may be connected to identity theft or fraud. A fraud alert tells potential lenders to take extra steps to verify your identity before opening new credit in your name. That can help stop new fraudulent accounts from being added while you dispute the inaccurate information.
However, a fraud alert does not remove incorrect information by itself. To correct credit report errors, you usually need to file a dispute with the credit bureau and, when appropriate, with the company that reported the inaccurate information. The CFPB says consumers have the right to dispute credit report errors, and fixing an error generally means contacting both the credit reporting company and the company that supplied the information.
Last Updated: July 2026
Key Takeaways
- A fraud alert is most useful when credit report inaccuracies may come from identity theft, such as accounts, inquiries, addresses, or debts you do not recognize.
- It helps by warning lenders to verify your identity before granting new credit.
- It does not directly delete errors; you still need to dispute inaccurate items.
- An initial fraud alert is free, lasts one year, and only requires contacting one of the three major credit bureaus. That bureau must tell the other two to place the alert as well.
- A credit freeze may offer stronger prevention because it limits access to your credit report, while a fraud alert still allows lenders to see the report after verification.
Why Fraud Alerts Matter When Credit Report Errors Involve Fraud
A credit report inaccuracy can happen for several reasons. Some errors are simple data problems, such as a wrong balance, a misreported payment, or mixed information from someone with a similar name. Other inaccuracies are more serious because they may signal identity theft.
Examples of fraud-related inaccuracies include:
- A credit card, loan, or store account you never opened
- A hard inquiry from a lender you do not recognize
- An address where you never lived
- A collection account tied to a service you never used
- A sudden account balance or delinquency that does not match your records
In these cases, a fraud alert can be effective because it helps reduce the chance that the same stolen information will be used again. The FTC explains that fraud alerts make lenders verify your identity before granting new credit in your name.
Fraud Alert vs. Credit Dispute vs. Credit Freeze
| Option | What It Does | Best For | Limitation |
| Fraud alert | Tells lenders to verify your identity before approving new credit | Suspected identity theft or fraud-related inaccuracies | Does not remove existing errors by itself |
| Credit dispute | Asks the bureau or furnisher to correct or remove inaccurate information | Fixing incorrect accounts, balances, payments, inquiries, or personal details | Requires documentation and investigation |
| Credit freeze | Restricts access to your credit report | Stronger prevention against new fraudulent credit accounts | You may need to lift it before applying for credit |
| Identity theft report | Documents identity theft through FTC or law enforcement channels | Confirmed identity theft and fraudulent accounts | Requires careful follow-up with bureaus and creditors |
The most effective response is often a combination: place a fraud alert, review all three credit reports, dispute inaccurate items, and consider a credit freeze if you are worried that someone may continue using your information.
How a Fraud Alert Helps With Credit Report Inaccuracies
1. It warns lenders that fraud may be involved
A fraud alert places a notice on your credit file. This notice tells creditors that you may be a victim of fraud or identity theft. That matters because some credit report inaccuracies are not just clerical mistakes; they are signs that someone may be trying to use your identity.
2. It adds an identity-verification step
The main value of a fraud alert is not that it “fixes” the report. Its value is prevention. Before opening a new account, lenders are expected to take reasonable steps to confirm that the applicant is really you. AnnualCreditReport.com explains that a fraud alert requires creditors to verify that you are the person adding new credit accounts or changing limits on existing accounts, usually by contacting the phone number you provide.
3. It can slow down repeat fraud
If an inaccurate account appeared because someone already used your personal information, the risk may not be over. The same person may try to open another account. A fraud alert can make that harder.
This is why a fraud alert is effective as a protective response to inaccuracies, not as the only correction method.
4. It gives you time to dispute the errors
Credit report disputes can take time. The FTC says credit bureaus generally have 30 days to investigate disputes after they receive them. During that window, a fraud alert can reduce the chance of additional unauthorized accounts appearing while the existing inaccurate items are being reviewed.
5. It is free and does not hurt your credit score
A fraud alert is free. Placing one does not directly lower your credit score, although it may slow down instant credit approvals because lenders may need to verify your identity manually. AnnualCreditReport.com notes that a fraud alert does not affect your credit score, but the extra verification steps may slow the approval process.
What a Fraud Alert Does Not Do
A fraud alert is helpful, but it has limits.
It does not:
- Automatically remove inaccurate accounts
- Guarantee that every lender will stop fraud
- Block all access to your credit report
- Replace the official dispute process
- Prove that every disputed item is fraudulent
This distinction is important. If your report has a wrong balance, incorrect late payment, duplicate account, or outdated information, a fraud alert alone is usually not enough. You should dispute the specific error with the credit bureau and the business that reported it. The FTC states that both the credit bureau and the business that supplied the information must correct information that is wrong or incomplete, and they must do it for free.
When You Should Consider Placing a Fraud Alert
A fraud alert may be appropriate when:
- You see accounts or inquiries you do not recognize
- Your Social Security number or personal information may have been exposed
- You received bills or collection notices for accounts you never opened
- Your credit report shows an unfamiliar address tied to suspicious accounts
- You suspect someone is applying for credit in your name
- You are disputing items that appear to be connected to identity theft
If you only see a simple reporting error, such as a payment marked late when you paid on time, start with a dispute and supporting documents. If the error looks suspicious or connected to unauthorized activity, add a fraud alert.
Read More:
Which of the Following Is a Variable Expense?
How to Place a Fraud Alert
You only need to contact one of the three major credit bureaus:
- Equifax
- Experian
- TransUnion
According to the FTC, when you place an initial fraud alert with one bureau, that bureau must tell the other two to place an alert on your credit report.
There are three common types of alerts:
| Fraud Alert Type | Who It Is For | How Long It Lasts |
| Initial fraud alert | People who are or may be affected by identity theft | One year |
| Extended fraud alert | People who have experienced identity theft and have an FTC identity theft report or police report | Seven years |
| Active duty alert | Eligible military servicemembers | One year |
If you are a confirmed identity theft victim, an extended fraud alert may be more appropriate than an initial alert. The FTC says an extended fraud alert requires an FTC identity theft report from IdentityTheft.gov or a police report.
What to Do After Placing a Fraud Alert
Step 1: Get your credit reports
Review your reports from Equifax, Experian, and TransUnion. AnnualCreditReport.com states that free weekly online credit reports are available from the three major credit reporting companies.
Step 2: List every inaccurate item
Create a simple record that includes:
- Bureau name
- Account name
- Account number, if shown
- Why the item is inaccurate
- Whether it may involve fraud
- Documents that support your position
Step 3: File disputes with the bureaus
Dispute the item with every credit bureau that shows the error. The CFPB recommends explaining what is wrong, why it is wrong, and including copies of supporting documents.
Step 4: Contact the company that reported the information
The company that supplied the information, often called a furnisher, may also need to investigate. Examples include banks, lenders, credit card issuers, landlords, utilities, or debt collectors.
Step 5: Report identity theft if needed
If you believe the inaccuracy came from identity theft, report it through IdentityTheft.gov. The FTC describes IdentityTheft.gov as the federal government’s one-stop resource to help people report and recover from identity theft.
Step 6: Consider a credit freeze
A fraud alert tells lenders to verify your identity. A credit freeze is stronger because it generally prevents new credit accounts from being opened while the freeze is in place. The FTC says a credit freeze is free and does not affect your credit score.
Practical Example
Suppose your credit report shows a store credit card you never opened. You also see a hard inquiry from the same store.
A fraud alert helps because it warns future lenders to verify your identity before approving new accounts. But to fix the current problem, you still need to dispute the store card and inquiry with the bureau that shows them. You may also need to contact the store card issuer, file an identity theft report, and consider freezing your credit.
That is why the best answer is: placing a fraud alert is effective because it helps prevent further fraudulent activity while you work to correct the inaccurate information.
Common Mistakes to Avoid
Mistake 1: Thinking a fraud alert deletes errors
It does not. You must dispute inaccurate information separately.
Mistake 2: Contacting only the lender, not the bureau
For credit report corrections, you often need to contact both the bureau and the company that supplied the information.
Mistake 3: Ignoring small unfamiliar details
A wrong address or unknown inquiry can be a clue that someone used your information.
Mistake 4: Using a fraud alert when a freeze is more appropriate
If you believe your personal information is actively being misused, a freeze may provide stronger protection than an alert.
Mistake 5: Failing to keep records
Save copies of dispute letters, confirmation numbers, credit reports, identity theft reports, police reports, and mail receipts.
FAQs
Does a fraud alert remove inaccurate information from my credit report?
No. A fraud alert does not remove inaccurate information. It warns lenders to verify your identity before approving new credit. To remove or correct inaccurate information, you need to dispute the item with the credit bureau and, when appropriate, the company that reported it.
Why is placing a fraud alert effective if my credit report is inaccurate?
It is effective when the inaccuracy may be caused by fraud or identity theft. It helps prevent new fraudulent accounts from being opened while you investigate and dispute existing errors.
Is a fraud alert better than a credit freeze?
Not always. A fraud alert allows lenders to access your report after taking verification steps. A credit freeze generally restricts access to your report, which can make it stronger for preventing new accounts. The better choice depends on your situation.
How long does a fraud alert last?
An initial fraud alert lasts one year. An extended fraud alert lasts seven years and is generally for people who have experienced identity theft and can provide an FTC identity theft report or police report.
Do I need to contact all three credit bureaus to place a fraud alert?
For an initial fraud alert, you only need to contact one of the three major credit bureaus. The bureau you contact must notify the other two.
What should I do first: dispute the error or place a fraud alert?
If the error looks like ordinary inaccurate reporting, start with a dispute. If it looks like fraud or identity theft, place a fraud alert quickly, then gather your reports and dispute the inaccurate items.
Conclusion
Placing a fraud alert is an effective way of dealing with credit report inaccuracies when those inaccuracies may be connected to fraud or identity theft. It does not erase errors, but it can stop the problem from getting worse by warning lenders to verify your identity before approving new credit.
The safest approach is to use a fraud alert as one part of a broader response: check all three credit reports, dispute inaccurate items, contact the companies that reported them, report identity theft if needed, and consider a credit freeze for stronger protection.
Sources:




Comments 1